Short answer
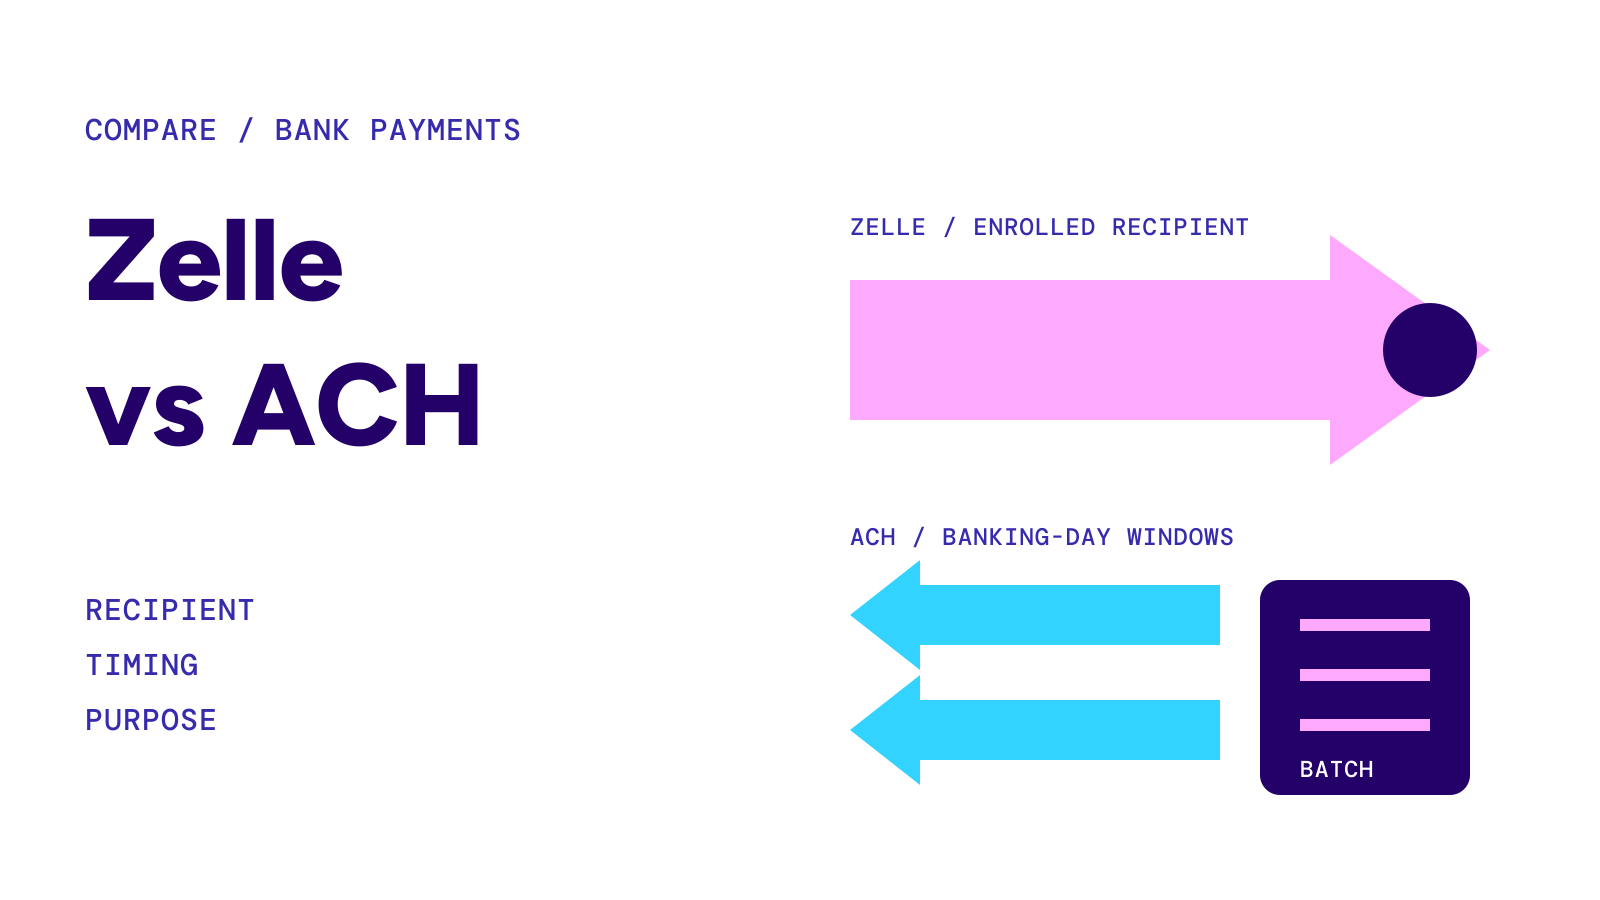
Zelle vs ACH is a choice between a bank’s person-to-person payment option and a broader network used for deposits, bill payments and transfers. Zelle usually reaches an enrolled recipient within minutes. ACH uses banking-day processing and settlement. Choose by the recipient, purpose, deadline and bank’s actual offer, rather than assuming every “bank transfer” works the same way.
On this page
Start with the payment you need to make
A friend who already uses Zelle and a company collecting a recurring bill are different situations. Zelle uses an enrolled email address or U.S. mobile number to direct money to an eligible bank account. ACH supports direct deposits and authorized payments, including credits that push money out and debits that pull it in.
That distinction matters when someone gives you payment instructions. If a company asks for account details and an ACH authorization, sending money to an email address is not an equivalent instruction. Follow the payment route the recipient accepts and verify unfamiliar instructions independently.
| Question | Zelle | ACH |
|---|---|---|
| Typical purpose | Send money to people you know and trust | Direct deposit, bills and bank transfers |
| Recipient details | Enrolled email or U.S. mobile number | Bank-account instructions or an authorized debit arrangement |
| Timing | Typically minutes for enrolled recipients | Same-day or later banking-day processing |
| Consumer fee | Usually none; confirm with the bank | Depends on the bank, service and transfer option |
| Limit | Set by the bank or credit union | Check the bank’s customer limit and available service |
| Cancellation | Only before the recipient enrolls | Depends on the instruction, payment stage and applicable process |
Sources: Zelle timing, Zelle cancellation, Nacha’s ABCs of ACH and Nacha reversals · Checked on October 21, 2026.
Minutes and banking days are different promises
Zelle describes money sent to an enrolled recipient as typically available within minutes. That wording is not a guarantee for every attempted payment. If a payment is missing, check its status and the recipient’s enrolled contact before sending again. Our Zelle payment pending guide handles that diagnosis.
Nacha says ACH payments can process the same business day or be scheduled for the following day or two business days later. Settlement depends on banking days; weekends and Federal Reserve holidays interrupt that calendar. The customer’s bank also determines which service it offers and its submission deadline.
Do not confuse the network’s capability with the option selected in your app. An ACH transfer labeled standard does not become Same Day ACH because the recipient needs it urgently. Read same day ACH and the confirmation screen before relying on a same-day arrival.
Fees and limits need an account-specific check
Zelle says consumer payments are typically fee-free, while advising customers to confirm their bank’s policy. It does not set one universal customer sending limit. For ACH, the amount your bank permits and any expedited-transfer charge belong to that bank’s service.
The Same Day ACH network ceiling is not your personal transfer allowance. A bank can offer a lower customer limit or not offer that option in its consumer app. Use our ACH transfer limit table to locate sourced bank policies, then check your own account’s current terms.
A useful comparison has three entries: the fee you will actually pay, the amount you can send and the delivery date offered for this transaction. A generic “free bank transfer” label supplies none of the last two.
Do not choose ACH just because you hope to reverse it
An ACH reversal is a defined correction process, not a general undo button for buyer’s remorse. Nacha’s rules address improper reversals and their return processes. Cancellation, an unauthorized-payment dispute and correcting a mistaken entry are separate questions; see can an ACH transfer be reversed.
With Zelle, a payment to an enrolled recipient cannot be canceled through the payment flow. Zelle also says it does not provide purchase protection. For an unfamiliar seller, speed is not a reason to ignore that limitation.
Warning
If a payment is unauthorized or you suspect fraud, contact your bank through its official channel promptly. Do not assume that either method guarantees a refund, or send a replacement before checking the original payment.
Which fits these situations?
- Repaying a trusted friend: Zelle can fit if both accounts are eligible and the enrolled contact is correct.
- Receiving wages or a recurring benefit: Follow the payer’s direct-deposit instructions rather than substituting a personal Zelle payment.
- Moving money between your own banks: Compare the external-transfer service’s limit and delivery date with the options your accounts actually support.
- Paying a new online seller: Look for an appropriate protected purchase method. Neither a fast Zelle payment nor the word ACH establishes purchase protection.