Short answer
An ACH transfer can be reversed only in some cases. Under Nacha’s rules, the sender can reverse it only to fix its own error, such as a duplicate payment, a wrong amount, a wrong date or the wrong account, and only within five banking days of settlement. You cannot reverse a payment because you changed your mind, but you can dispute an unauthorized debit with your bank and stop future automatic payments.
On this page
ACH is the network behind direct deposits, bill payments and transfers between banks. “Reversing” a payment means different things depending on which side of it you are on, so start with the situation that matches yours.
At a glance
- Who can reverseOnly the sender of the payment (the Originator), through its bank
- Allowed reasonsDuplicate payment, wrong amount, wrong date, wrong account
- DeadlineWithin five banking days of the original settlement date
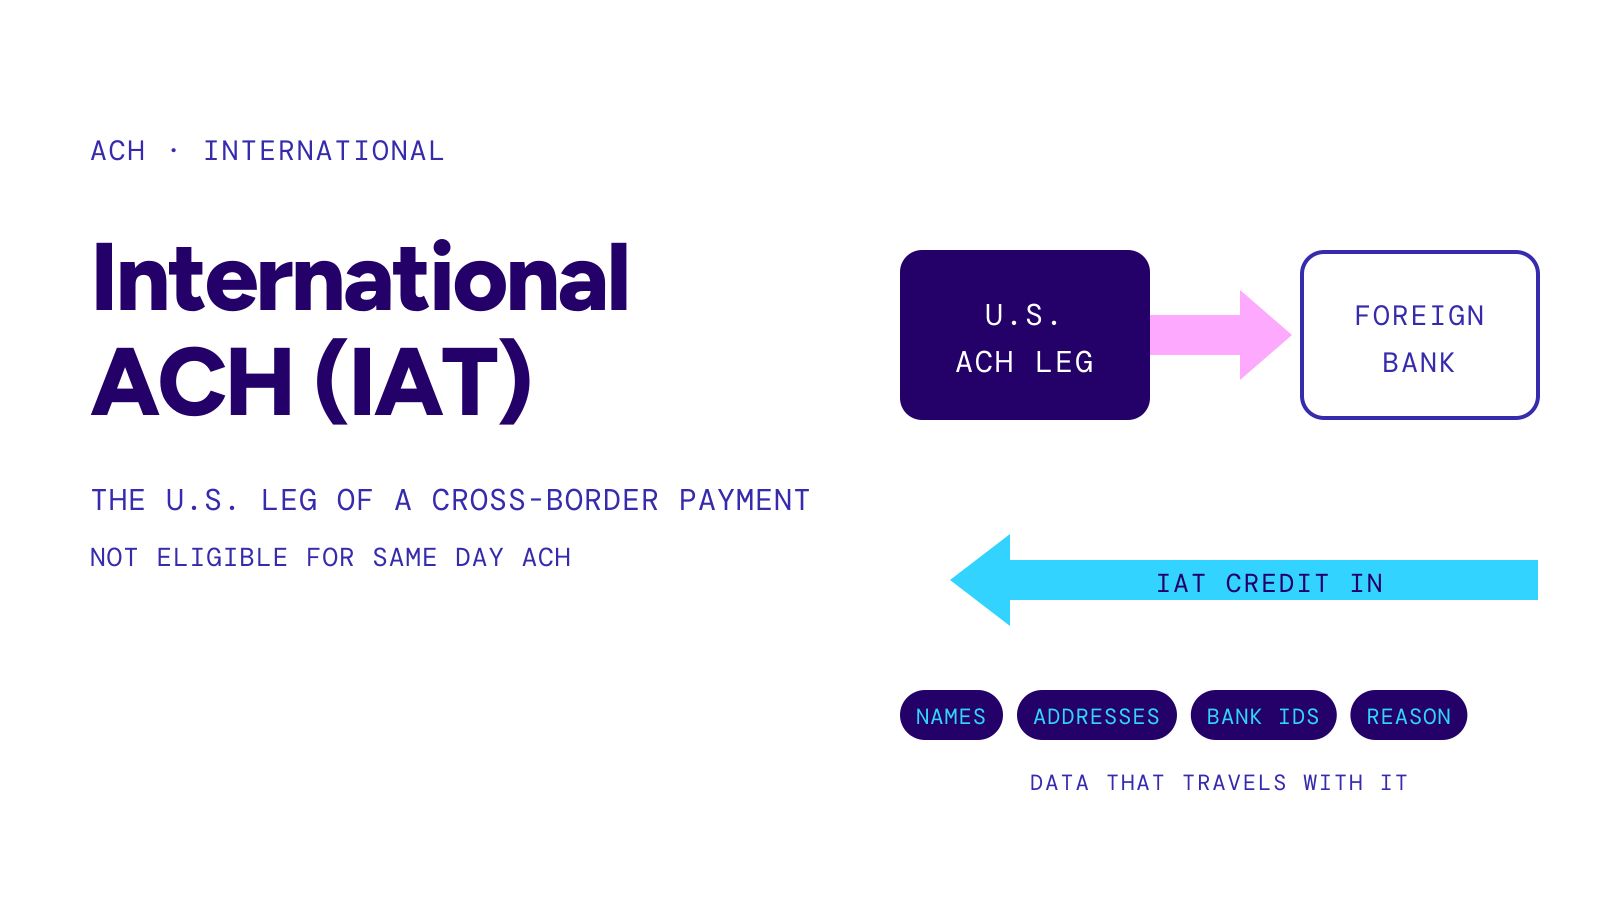
- Not allowedFraud, a disputed but legitimate payment, a change of mind, international ACH payments (IAT)
- Marked as“REVERSAL” in the company entry description on your statement
Source: Nacha: A Second Chance: Understanding ACH Reversals · Checked on October 10, 2026
Which situation are you in?
| Your situation | What you can do | Time limit |
|---|---|---|
| You sent an ACH payment by mistake | Ask your bank at once whether a reversal is possible | Five banking days after settlement |
| A company took money you did not authorize | Report it to your bank as an error | 60 days after the statement showing it |
| You want to stop a future automatic payment | Give your bank a stop-payment order and revoke the authorization with the company | At least three business days before the payment |
| A deposit to you was reversed | Ask your bank; an improper reversal can be returned | Report it promptly |
Sources: Nacha: A Second Chance: Understanding ACH Reversals, CFPB: Regulation E, section 1005.10, CFPB: Regulation E, section 1005.11 · Checked on October 10, 2026
If you sent the payment by mistake
A reversal is a new ACH entry that pulls back an erroneous payment. Nacha allows it only for errors that start with the sender: a duplicate, an incorrect amount, a payment on the wrong date or one sent to an unintended account. It has to be sent within five banking days of the original settlement date, and the amount must match the original.
A reversal is not guaranteed to bring money back. If the money is no longer in the receiving account, the reversal is returned and nothing is collected. Some banks send reversals only on their clients’ behalf, so call your bank’s support line rather than waiting.
Warning
A reversal cannot be used to recover money sent to a scammer. Nacha says that if you deliberately sent a payment to an account and later learn it belongs to a fraudster, a reversal is not the remedy: ask your bank what it can do, and report the fraud. Never pay a “fund recovery” service.
If a company debited your account without permission
Regulation E treats an unauthorized electronic transfer as an error. Tell your bank within 60 days after it sends the statement that first shows the debit. The bank must investigate and decide within 10 business days. If it needs longer, it can take up to 45 days, but it must provisionally credit your account while it investigates.
Nacha’s consumer guidance says the same in plain terms: if you do not recognize the company on your statement and nobody on the account authorized the payment, contact your bank soon, because the time to report is limited.
Timeline
- The debit postsan unfamiliar company takes money from your account
- Within 60 days of the statementyou report it to your bank, by phone or in writing
- Within 10 business daysthe bank decides whether an error occurred
- Up to 45 daysif it needs longer, it credits your account provisionally while it finishes
Source: CFPB: Regulation E, section 1005.11 · Checked on October 10, 2026
If you want to stop an automatic payment
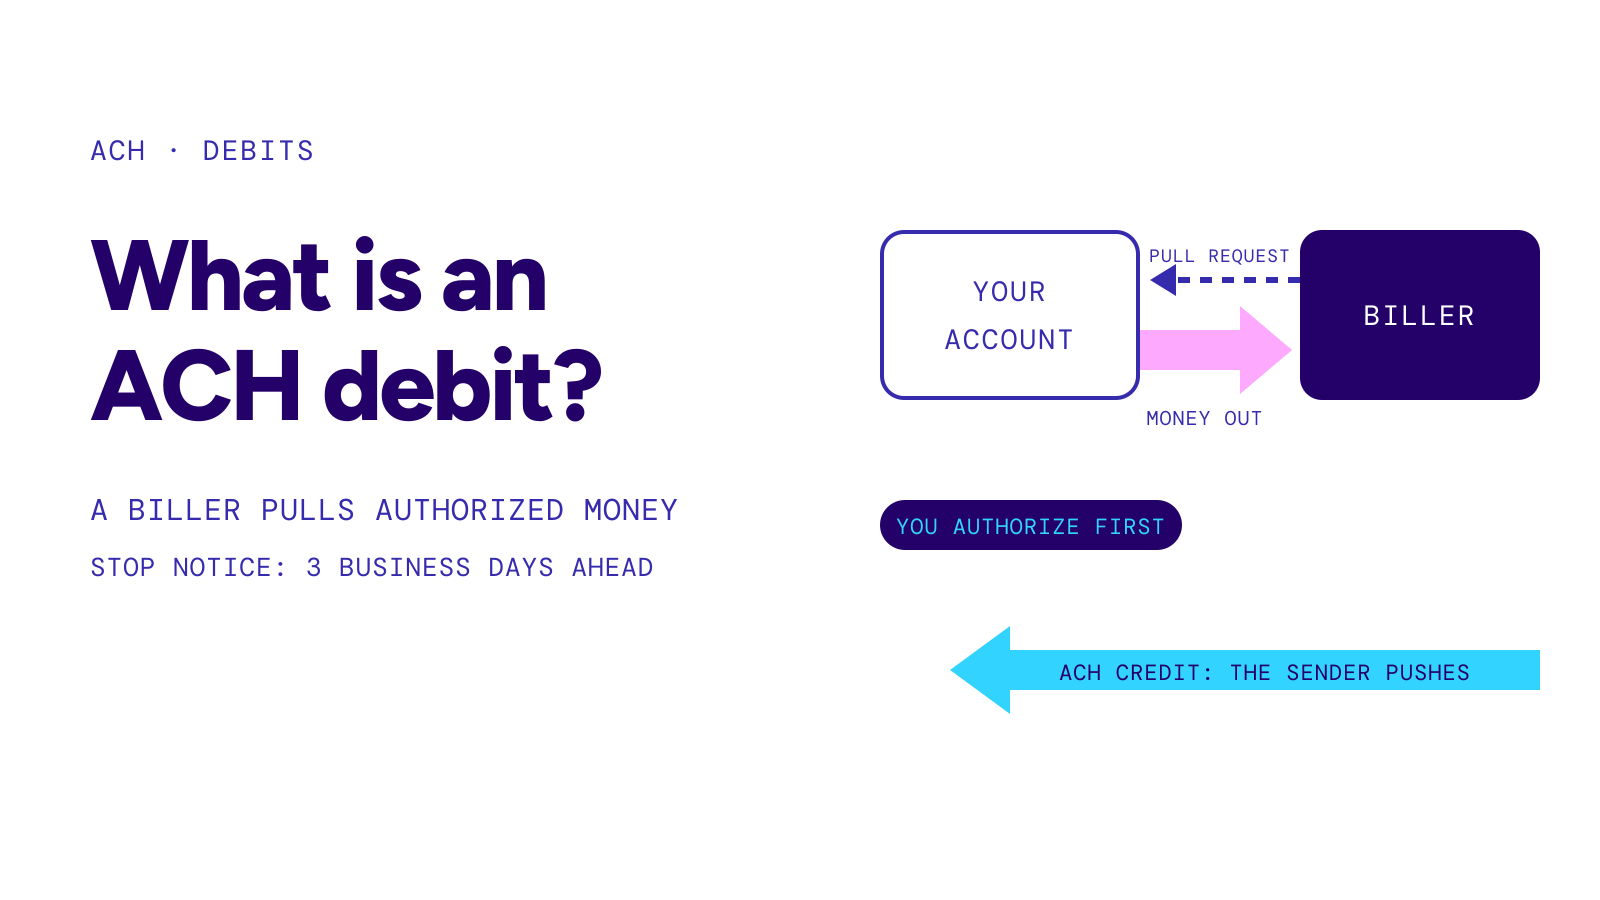
You can stop a preauthorized debit, such as a gym or loan payment, by telling your bank at least three business days before it is scheduled. You can do it by phone; the bank may ask for written confirmation within 14 days. The CFPB also recommends revoking the authorization with the company itself. Once you have revoked it and told your bank, later debits by that company are unauthorized.
Sources: CFPB: Regulation E, section 1005.10, CFPB: How do I stop automatic payments from my bank account? · Checked on October 10, 2026
If a deposit to you was reversed
An employer or company that paid you twice, or paid the wrong amount, may reverse the error. The entry shows “REVERSAL” in its description and matches the original amount. A reversal for any other reason is improper: under Nacha’s rules your bank can return an improper reversal on a consumer account within 60 days of receiving your claim.
Source: Nacha: Reversals and Enforcement · Checked on October 10, 2026
How ACH compares with Zelle and wires
An ACH payment can be reversed for the errors above or returned under the network’s rules. A wire is final once sent, and a Zelle payment to an enrolled recipient cannot be canceled. See ACH vs wire transfer and can you cancel a Zelle payment. If your transfer is only late, not wrong, see ACH transfer pending and how long does ACH take.