Short answer
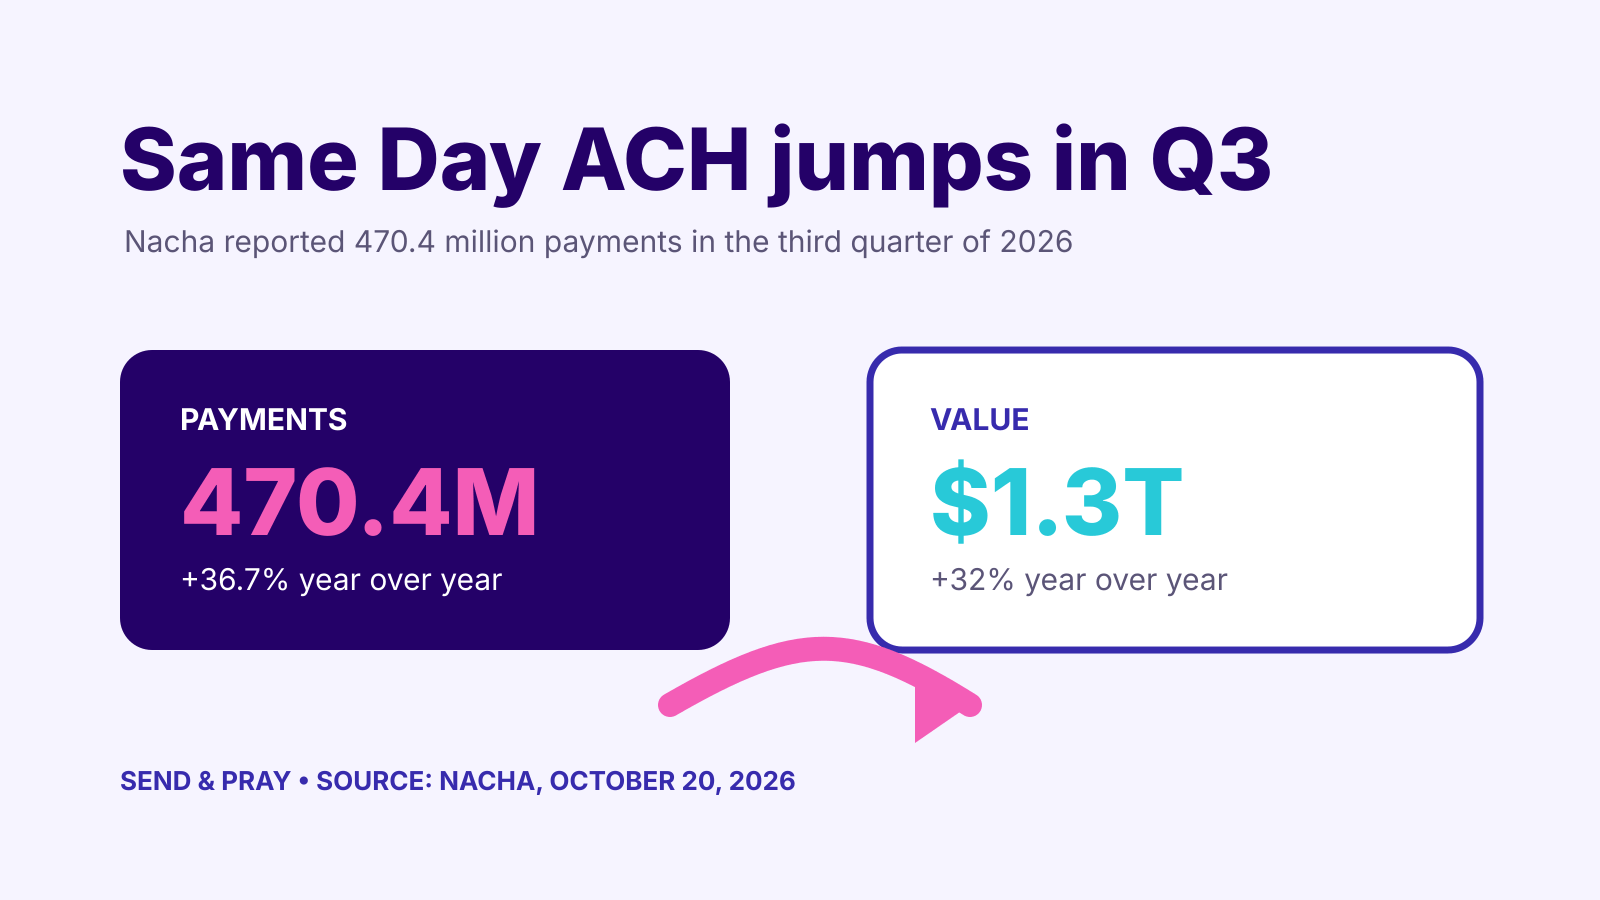
Nacha reported 470.4 million Same Day ACH payments in the third quarter of 2026, up 36.7% from a year earlier. Their value reached $1.3 trillion. The figures describe the network as a whole; they do not change a bank’s cutoff or guarantee that a particular payment will arrive the same day.
On this page
Nacha’s October 20 release shows faster-payment use rising much more quickly than the ACH Network overall. Total network volume rose 5.9% year over year in the quarter, while Same Day ACH volume rose 36.7%.
What changed
- Report dateOctober 20, 2026
- Same Day ACH volume470.4 million payments, up 36.7% year over year
- Same Day ACH value$1.3 trillion, up from $970.4 billion
- All ACH volume9.3 billion payments, up 5.9%
- All ACH value$25.6 trillion, up 10.2%
- Who it affectsbanks, payment providers and businesses using the ACH Network
Source: Nacha: Same Day ACH Growth Propels the ACH Network Forward in Third Quarter of 2026 · Published October 20, 2026 · Checked October 26, 2026
Same Day ACH grew faster than the network
Same Day ACH accounted for about one payment in twenty across the network during the quarter. Its share of value was smaller, but the $1.3 trillion total was nearly one-third higher than in the third quarter of 2025.
Nacha also reported 1.3 billion Same Day ACH payments worth more than $3.6 trillion over the first nine months of 2026. Those year-to-date figures were up 30% in volume and 28.7% in value.
The comparison is year over year. It does not say that a payment sent in September moved 36.7% faster than one sent a year earlier. “Growth” here means more payments and more value using the same-day service.
Business payments drove part of the increase
Business-to-business ACH volume reached nearly 2.3 billion payments in the quarter, up 9.7% from a year earlier. Nacha linked that growth to organizations moving away from checks.
Healthcare ACH claim payments to providers also increased, rising 2.6% to more than 144 million payments.
These categories overlap with the wider 9.3 billion network total. They should not be added to Same Day ACH as if they were separate networks.
What this does not change for a sender
A network statistic does not override a bank’s customer cutoff. A payment can qualify for Same Day ACH only if the bank or provider offers the service, accepts the instruction in time and submits it into an eligible processing window.
The sender may also see a bank cutoff earlier than the network’s own deadline. That gives the bank time to check and prepare the file. Same Day ACH explains the service and the difference between network windows and customer-facing cutoffs.
Same Day ACH is also not the same as an instant-payment rail. The ACH payment moves in scheduled same-day processing windows. FedNow and RTP are designed for immediate availability between participating institutions. Our guide to how long ACH takes covers the timing distinction.
Why the value figure needs context
The $1.3 trillion figure is the total value of Same Day ACH payments during the quarter. It is not the amount outstanding at one time and not a measure of consumer balances.
Dividing total value by volume would produce an average, but that average would mix payroll, business payments and other uses. It would not describe a typical consumer transfer. Nacha’s release does not publish a consumer median.
The safest reading is the direct one: more payments and more dollars used the same-day option than a year earlier.
Source
- Nacha, “Same Day ACH Growth Propels the ACH Network Forward in Third Quarter of 2026”, October 20, 2026.
Figures are Nacha’s network statistics. This item does not provide payment, legal or financial advice.